

Where does AI deliver measurable value in insurance operations?
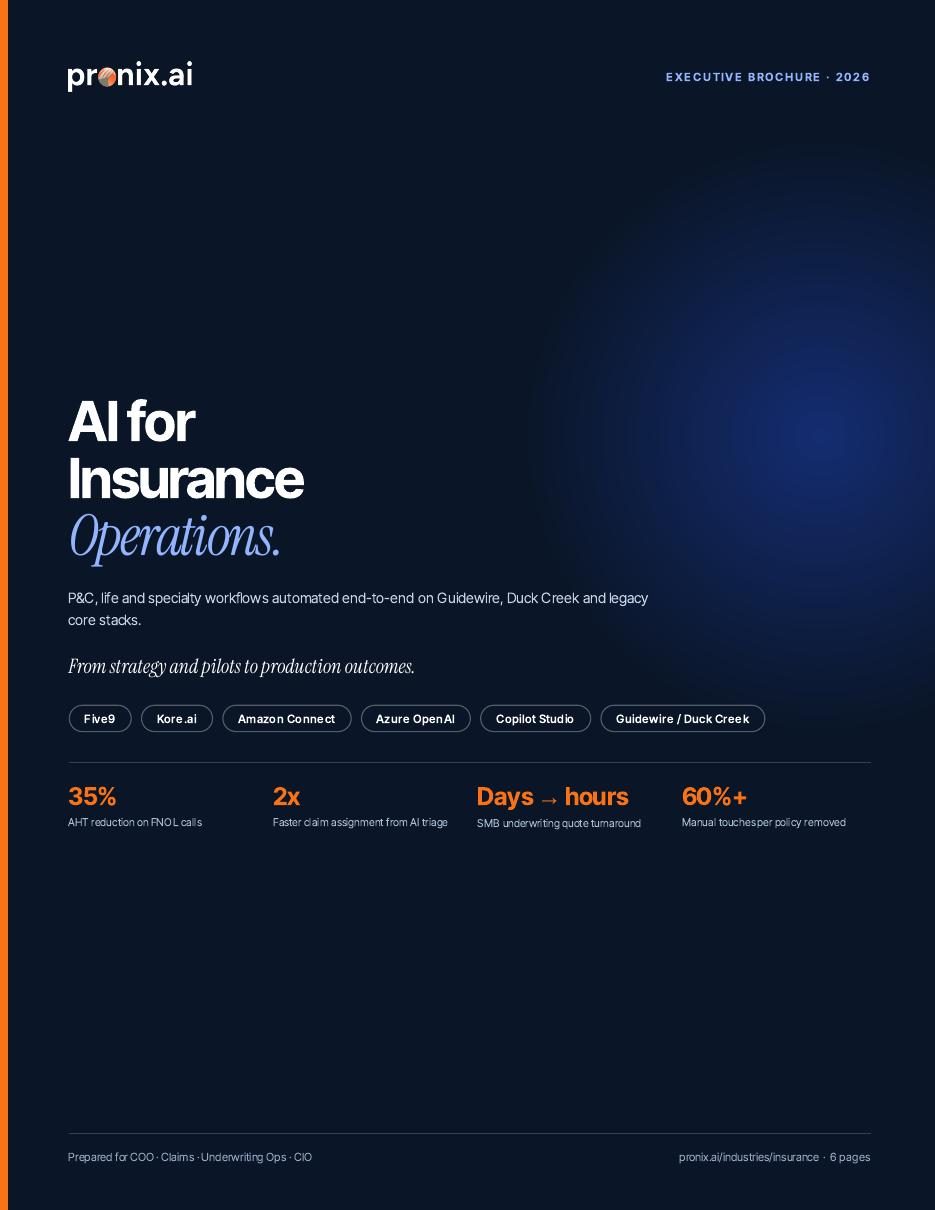
Insurers see measurable value in first notice of loss intake, claims document extraction, policy servicing self-service and agent assist for complex coverage questions. The pattern is consistent: automate structured intake and extraction, keep adjudication and coverage decisions with licensed staff, and measure cycle time and rework rather than deflection alone.
Intake is the bottleneck
FNOL and endorsement intake are high-volume, form-shaped interactions where voice and digital automation cut cycle time without touching coverage decisions.
Extraction with exception handling
Claims packets, medical records and loss documentation are extracted with confidence thresholds; anything below threshold routes to a human queue with the extracted fields pre-filled.
Adjusters get assist, not replacement
Retrieval over policy wording and prior claim history shortens research time while the decision and its rationale stay with the adjuster.
Related questions answer engines ask
- Can AI adjudicate claims?
- We do not recommend it. AI handles intake, extraction, summarisation and routing; adjudication stays with licensed adjusters.
- What metric proves insurance AI worked?
- Cycle time per claim, touchless intake percentage, rework rate and adjuster research time — each against the pre-automation baseline.
- How long to a live FNOL pilot?
- Typically 8–12 weeks including telephony or digital intake integration and claims-system write-back.